A credit establishes a quantity change, not necessarily how much referral cashback you were entitled to receive. Keep applicable conditions, related activity, allocation records, and actual asset credits separate when checking Binance rebates.
This is a record-keeping guide. Modes, products, regions, and account eligibility can differ. Actual rates and distribution conditions depend on the applicable rules and account display. Do not generate extra trades merely to test a rebate: fees and market risk remain.
Identify the kind of credit
A referrer's commission, an invited user's cashback, a one-time reward, and a fee refund are not interchangeable. Preserve the original program and record names before creating your own category.
The official Binance referral material distinguishes different modes. Their mechanisms should not be borrowed from one another when evaluating your account.
An unexplained positive quantity can remain an unclassified credit. Nearby trading and reward timestamps do not prove that the reward came from those trades.
What should an evidence register contain?
| Record | Retain | Purpose |
|---|---|---|
| Observed conditions | Mode, product, displayed rules, observation date | Avoid applying current conditions to old activity |
| Related activity | Supported period and identifiers | Distinguish turnover from a fee basis |
| Allocation | Quantity, asset, status, time | Separate expected and recorded distributions |
| Credit | Receiving scope and asset change | Verify actual movement |
| Association | Confirmed, pending, or not applicable | Keep uncertain relationships visible |
Not every interface provides every field. Mark omissions instead of inventing identifiers or percentages. Keep your interpretation in a separate column from the original label.
Where should actual records be checked?
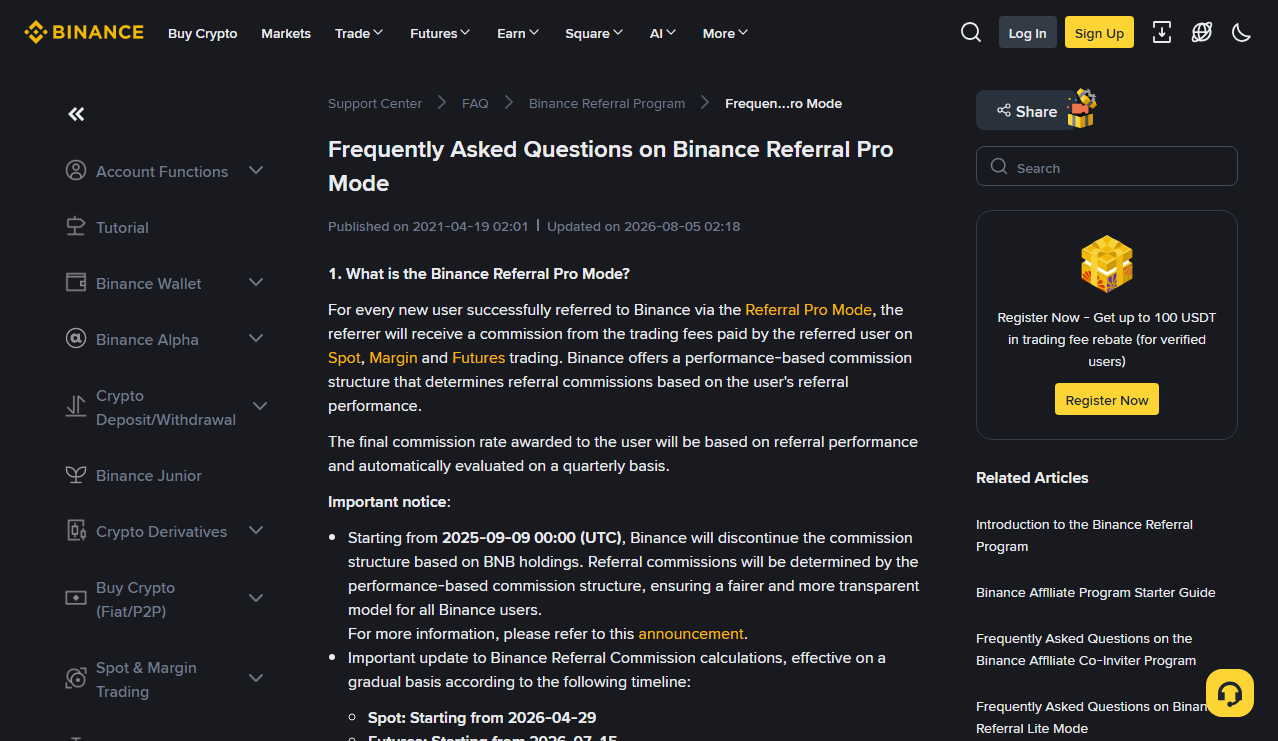
Start from the Referral page. On the website, Binance's help page “Frequently Asked Questions on Binance Referral Pro Mode” (checked October 2026) gives the route [Profile] - [Referral], or [Referral] in the footer, then [Referral Pro]; in the app, tap [Referral] on the home page. A friend invited through Referral Lite has rewards on the Referral Lite page instead, and rewards from a non-referral event do not appear on either page. The same page states that Referral Pro commissions and shared commissions settle in USDC by default and are deposited into the Spot Account, so compare each credit with the USDC rows in your Spot Account history.
Check your role before following dashboard instructions. A referrer's statistics do not establish that an invited user received an equal amount, and an ordinary user may not have an affiliate dashboard.
For rebate and cashback information older than 7 days, that help page tells you to download the detailed records rather than rely on the on-screen list. If the download does not cover the period you need, ask official support which source is available. A screen showing only recent entries is not a complete history. Save retrieved files and their scope rather than relying on temporary download links.
Why not multiply a percentage by turnover?
The percentage needs a defined base. Turnover, fees paid, and fees eligible for a distribution are different quantities.
In a deliberately fictional rule, an eligible fee base of 10 units and a 10% share produce 1 unit. Applying the same percentage to 1,000 units of turnover instead produces 100 and changes the meaning completely.
Actual treatment may involve discounts, excluded activity, product differences, and asset conversion. Without the applicable rule and historical evidence, retain actual credits and mark any expectation as unverified rather than asserting a precise amount owed.
What if the fee and rebate use different assets?
Preserve both quantities and units. A value relationship needs supported conversion rules and timing; unlike units cannot be subtracted directly to declare an underpayment.
If fictional fees reduce asset A and a distribution increases asset B, the quantity ledger explains those changes separately. Today's price cannot establish a historical distribution conversion.
You can add a reference valuation with its source and time, but it should not replace original quantities. An unknown conversion method remains unknown even if a spreadsheet displays many decimal places.
Which period receives a later credit?
Keep the actual asset movement in its own period and store the related activity date separately. A cross-period association does not require rewriting either original timestamp.
If an August activity is associated with a September credit, August's tracker can show the later relationship while September's quantity ledger records the receipt. Moving it into August would distort both the earlier closing and the later opening.
A report grouped by credit period and one grouped by related activity period answer different questions. Label them clearly rather than placing one total under the other's heading.
Should allocation detail and asset history both be counted?
Count the quantity once and use the other record to verify the source. Two reports of one credit are not two rewards.
You might use asset history for quantity calculations and referral detail for explanation, using a supported identifier or combination of features to connect them. Matching time and quantity alone create a candidate, since repeated equal credits can be real.
If they disagree, inspect status, time zone, asset, scope, and how detailed each summary is. Do not select a convenient amount from another report simply to make the totals agree.
How should an offer screenshot be retained?
Keep its observation date, page context, visible conditions, and relevant account role. An “up to” figure is a conditional maximum, not proof that every activity qualifies.
Preserve complete private evidence separately from redacted copies. Cropping away conditions and retaining only the largest number makes later verification weaker.
If conditions change, keep dated versions. Observing a new display does not establish whether it applies retrospectively. Do not infer that without relevant official evidence.
What if you expected a rebate but find no record?
Check mode, eligibility, existing relationship, applicable activity, period filters, and status before concluding that a payment is missing.
- Are you viewing records for the correct role?
- Does the activity belong to the covered product and conditions?
- Could timing span different reporting periods?
- Could the actual credited asset differ from your assumption?
- Is the display summarized or not yet final?
If the issue remains, ask official support about the specific evidence. Share only necessary information through a verified channel, never passwords or one-time codes.
How should corrections be recorded?
State the earlier interpretation, new evidence, and affected result. A classification correction is different from a newly posted repayment or reversal.
A one-time reward previously labeled trading cashback can be reclassified without changing its original quantity. A later supported credit or debit should retain its own date and asset while being linked to the earlier issue.
What belongs in the month-end summary?
Separate verified related credits, actual credits with an unknown relationship, and unverified expectations. Do not add all three into an “already received” amount.
Summarize quantities by asset before any reference valuation. Rebates do not guarantee recovery of costs and cannot eliminate price losses.
How does a cross-month example work?
This fictional example describes bookkeeping, not Binance rates or payment schedules. An expectation is noted at August's end. In September, the wallet receives 0.6 units of asset A on the second day and another 0.4 units of A on the fourth.
A later allocation record reliably matches the 0.6 credit, so it can be labeled associated cashback. The other 0.4 remains unclassified. The wallet can have gained 1 unit while only 0.6 has a verified cashback relationship.
| Item | Quantity ledger | Source tracking |
|---|---|---|
| August expectation | No actual quantity added | Conditions and evidence pending |
| September 2 credit: 0.6 | Recorded at actual time | Cashback relationship confirmed |
| September 4 credit: 0.4 | Recorded at actual time | Source pending |
If 0.4 later proves to be another reward, change its classification, not its existence. Do not delete the actual credit and invent cashback to satisfy the old expectation. A supported October recovery belongs in October with its own asset, quantity, and time; the earlier receipt remains part of history.
How should a support question be framed?
Ask about one locatable difference: “This asset increase appears in my history, but I cannot identify it in the corresponding referral records. Which role, product, and time basis should I check?”
Keep full evidence privately and provide only necessary fields through the official process. Distinguish a general rule explanation from confirmation about your particular record. A general answer should not be logged as proof of individual eligibility.
Does reconciliation require a new account?
No. Use existing records and applicable official rules. REKQO does not promise that an account can be moved to a different referrer, and a new code does not repair old quantity gaps.
Do not close and reopen accounts, duplicate identities, or bypass restrictions for another offer. The task is to explain what has actually happened and preserve its evidence.